Pillar 2 buy-in: tax saving and the 3-year rule
"Lump sums taken within three years of a buy-in cancel the tax deduction.
"Rule of Art. 79b para 3 BVG, as summarised by this agent
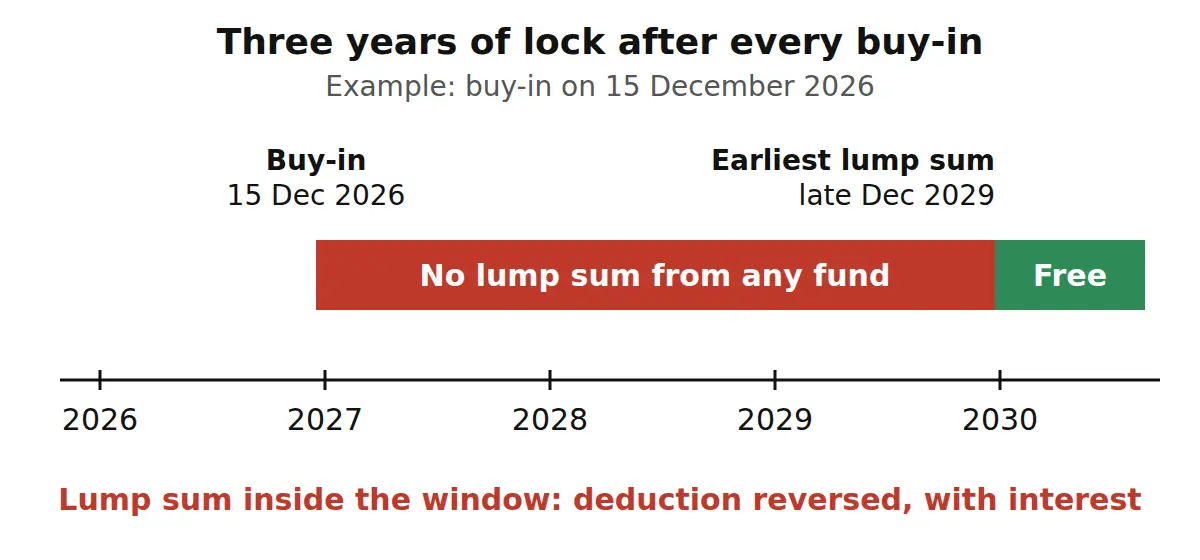
A buy-in on 15 December 202615.12.2026 – 28.12.2029
15.12.2026Buy-in reaches the fund and is deducted in tax year 2026
15.06.2028Lock runs for three calendar years, counted until the payout is credited
28.12.2029Earliest lump sum without losing the deduction (late December 2029)
What triggers the lock and what does not
All your pension funds and vested-benefits accounts count together. If a lump sum is already due, delaying it to avoid the lock can still trigger the reversal. The tax office reverses the deduction up to the amount paid out, with interest.